Systematic Books Reconciliation and Ledger Close
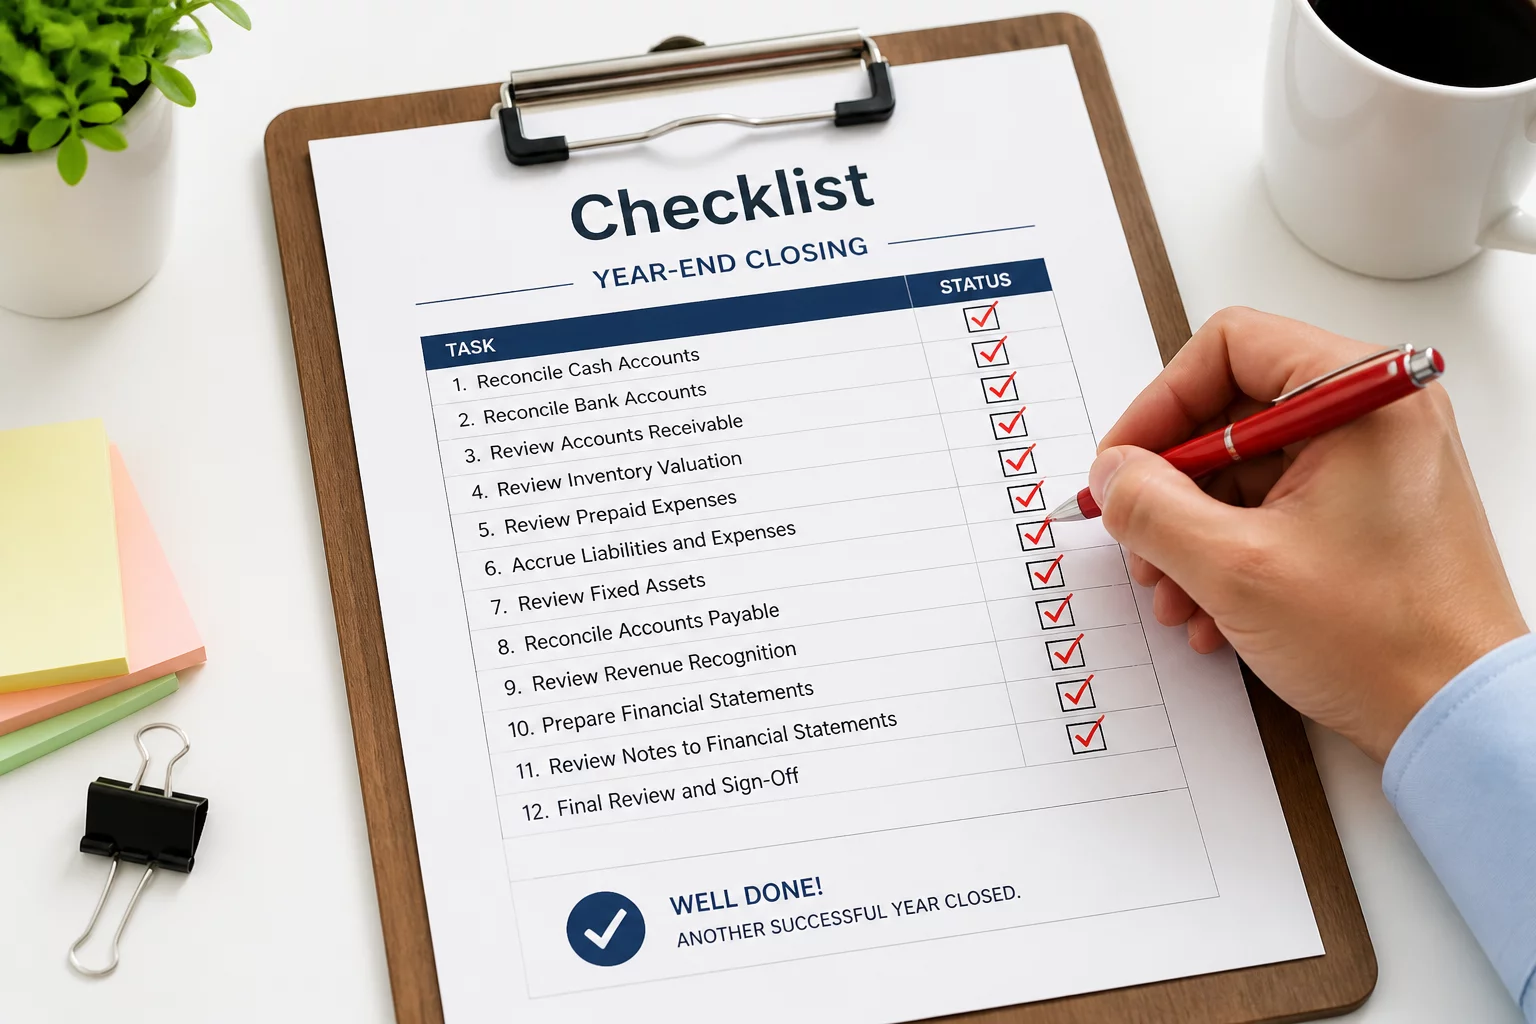
Closing fiscal periods demands strict attention to transactional integrity across every active cash account, payment gateway, and financing line. Unmatched deposits and lingering uncashed vendor disbursements distort financial ratios and invite unnecessary tax scrutiny. Verifying every single trial balance line against corresponding bank statements forms the fundamental baseline of your year-end posture.
Discrepancies often originate in delayed invoice recognition, merchant clearing fees, or unrecorded amortization schedules. Reconciling payroll summaries against quarterly Form 941 reports ensures employee withholdings mirror general ledger wage expenses. Identifying and resolving these ledger variances before January eliminates rush corrections when tax preparation deadlines arrive.
Critical Closing Benchmarks & Deadlines
- Reconciliation Target
- December 31, 2026
- Form 1099-NEC & MISC
- January 31, 2027
- Section 179 Cap (2026)
- $1,220,000 Allowance
- W-2 Recipient Distribution
- January 31, 2027
Operational Balance Sheet Audit and Asset Adjustments
Balance sheet integrity requires rigorous physical verification and inventory adjustments. Counting unsellable stock and writing down dead inventory lowers taxable net income while reflecting realistic working capital. Furthermore, review your fixed asset depreciation schedules, confirm newly acquired equipment placements into service before December 31, and formalize deductions for irrecoverable customer balances.
Five Core Mandates for Year-End Readiness
- Match all bank, merchant gateway, and payment card accounts directly to general ledger statements without residual unallocated amounts.
- Collect updated Form W-9 from every independent contractor receiving over $600 to ensure smooth 1099 distributions.
- Perform comprehensive physical inventory counts and record necessary scrap, spoilage, and obsolescence valuations.
- Review accounts receivable aging reports, clearing verified non-collectible balances to capture appropriate tax adjustments for uncollectible accounts.
Meticulous year-end financial preparation is not merely defensive compliance; it provides executives with an unvarnished blueprint of real operating performance.