The Mechanics of Statutory Withholding and Employer Contributions
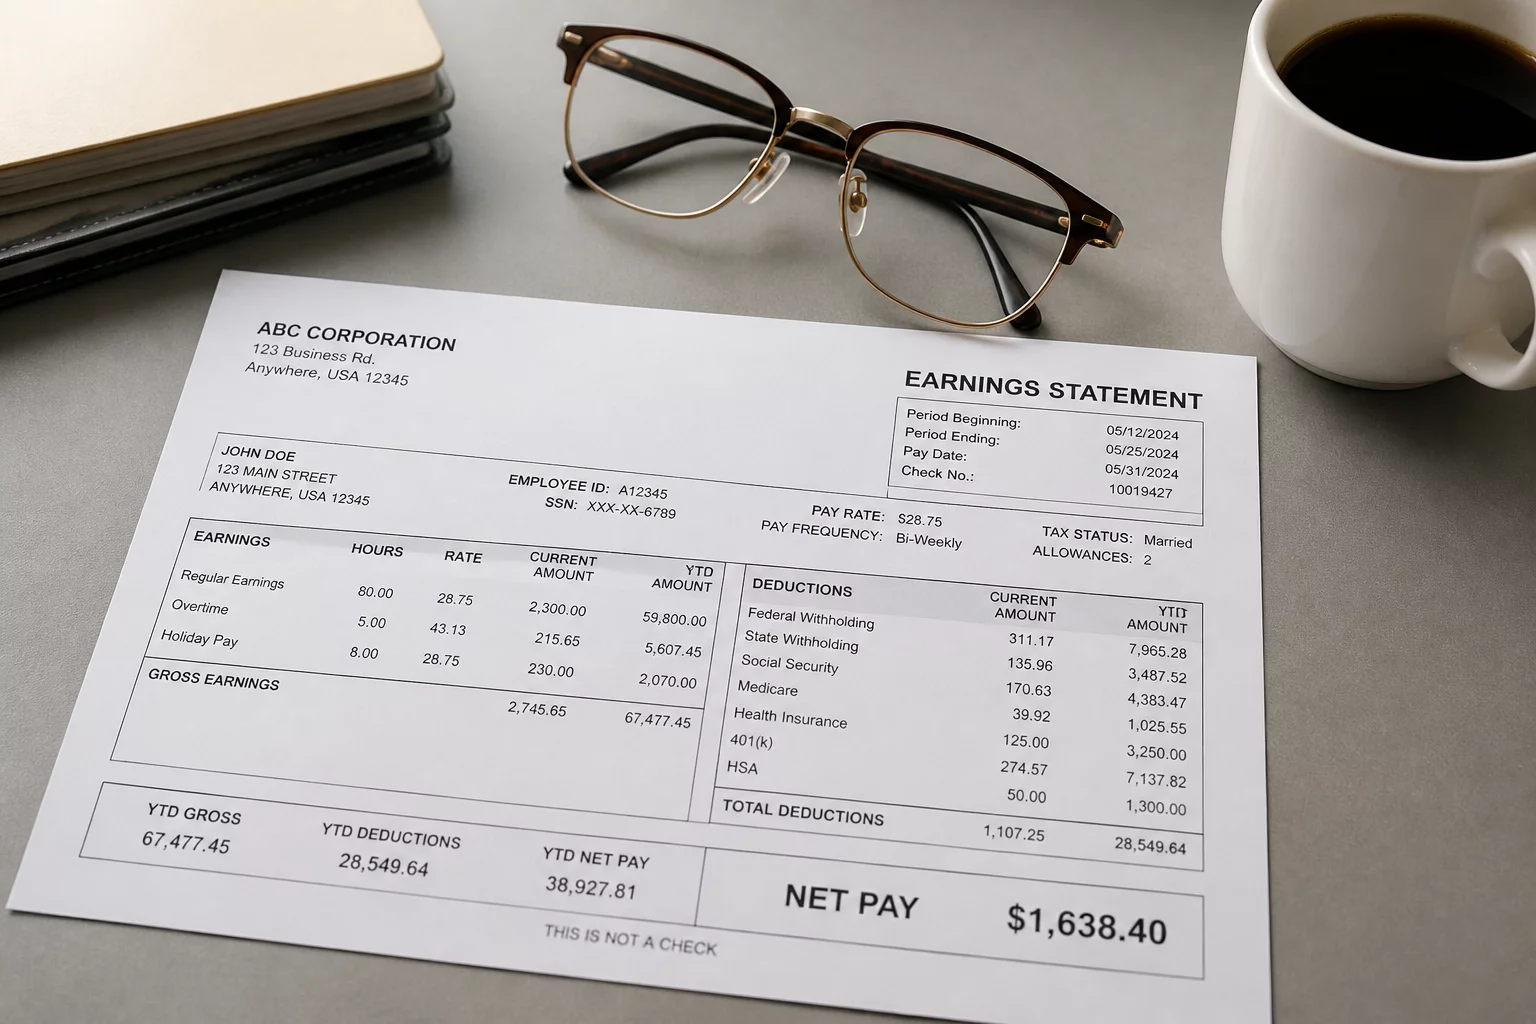
Every enterprise hiring staff encounters complex statutory obligations under the Federal Insurance Contributions Act alongside state-level withholding mandates. The payroll system requires employers to deduct specific percentages directly from gross compensation while contributing dedicated matching reserves from company funds. A failure to segregate trust fund taxes creates personal liability for company directors, making disciplined calculation processes paramount.
Statutory withholdings split into distinct buckets comprising federal income tax withholdings, Medicare contributions, Old-Age, Survivors, and Disability Insurance, and state unemployment program funding. Employers carry the legal duty to remit these collections promptly through the Electronic Federal Tax Payment System while maintaining granular ledger reconciliations for quarterly filings.
Key Payroll Metrics & Contribution Schedules
- Social Security (OASDI) Share
- 6.2% Employee + 6.2% Employer
- Medicare (HI) Contribution
- 1.45% Employee + 1.45% Employer
- Federal Unemployment (FUTA)
- 0.6% Effective Net (Max $42/worker)
- Form 941 Reporting Cycle
- Quarterly (Apr 30, Jul 31, Oct 31, Jan 31)
Mitigating Trust Fund Penalties and Multi-State Discrepancies
Payroll errors rarely stem from malice; instead, they arise from shifting employee tax residences, imprecise pre-tax deduction sequencing, and tardy deposit schedules. Business owners must implement standardized onboarding using validated Form W-4 declarations and establish isolated payroll escrow accounts to prevent routine operational expenses from absorbing collected tax liabilities.
Critical Payroll Protocols for Small and Medium Businesses
- Segregate payroll trust collections into a separate depository checking account immediately upon wage calculation.
- Audit worker classifications biannually to eliminate contractor misclassification risks under stringent DOL guidelines.
- Reconcile monthly EFTPS settlement transcripts against internal general ledger summaries prior to filing quarterly Form 941.
- Register promptly for State Unemployment Tax (SUTA) accounts whenever staff operate remotely across state boundaries.
Treating payroll withholdings as operational working capital is the single fastest way to encounter catastrophic IRS personal assessments. Strict segregation safeguards corporate security.